Example 0112 months
£400,000
Illustrative amount lent
- 2% arrangement fee
- £8,000
- Monthly interest
- £36,000
- Total investor income
- £44,000
- Total repayment
- £444,000
ROI: 11%Total illustrative return
 Contact
Fixed-return property opportunities
For investors considering deal-specific loans of £400,000 or more. This is property-backed lending with an agreed return.
The proposition
Each opportunity is assessed and presented individually. Investors receive the information needed to understand the property, funding requirement, proposed works, valuation, expected term, repayment strategy and material risks before making a decision.
The typical loan covers property purchase and refurbishment, with an expected project period of approximately 9–18 months.
Security
The proposed safeguards will include a first legal charge over the property (same security as a bank), personal guarantees and Pow Property funding agreed cost overruns.
Illustrative returns
Examples based on a 2% arrangement fee plus simple interest of 0.75% per month. Capital, the arrangement fee and accrued interest are normally paid together when the loan is repaid.
Illustrative amount lent
ROI: 11%Total illustrative return
Illustrative amount lent
ROI: 13.25%Total illustrative return
Illustrative amount lent
ROI: 15.5%Total illustrative return
These are simple illustrations, not an offer or guarantee. Each opportunity, term, security package and return is documented separately. Capital is at risk.
Your investor journey
Every opportunity is different, but the route from first conversation to repayment should always be easy to understand.
Speak privately with Mark about your objectives, likely amount and questions.
Review a specific property, funding requirement, proposed return and exit.
Consider the figures, works, valuation basis, risks and supporting evidence.
Independent solicitors complete the loan, first-charge and legal-advice process.
Capital is applied to the agreed property purchase and refurbishment.
Receive progress, milestone and material-change updates during delivery.
Capital, fees and accrued interest are normally repaid together on redemption.
Investor testimonials
Completed project evidence
Explore 13 completed projects and see how we acquired, transformed, refinanced and operated them. These historic figures demonstrate delivery; they are not a forecast for a future loan.
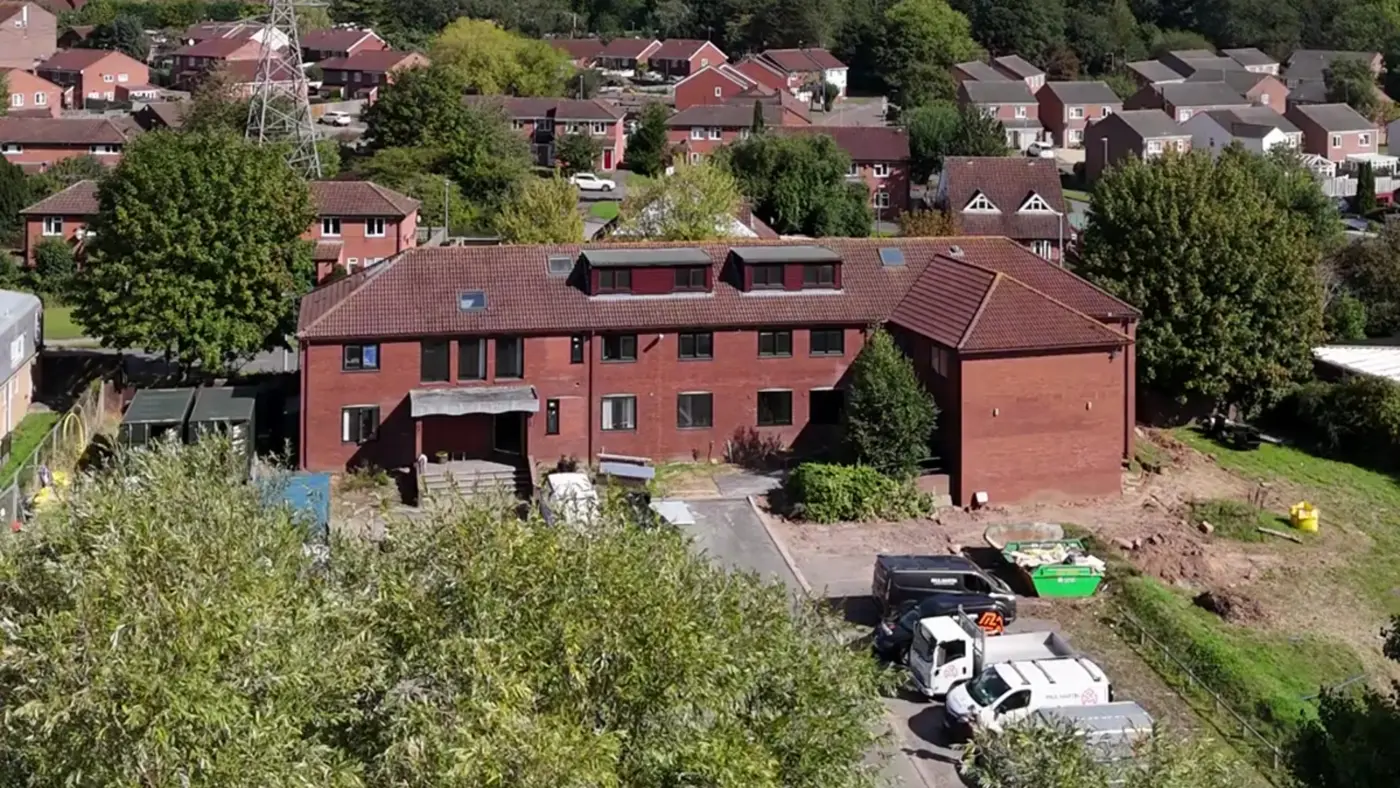
Commercial to residential
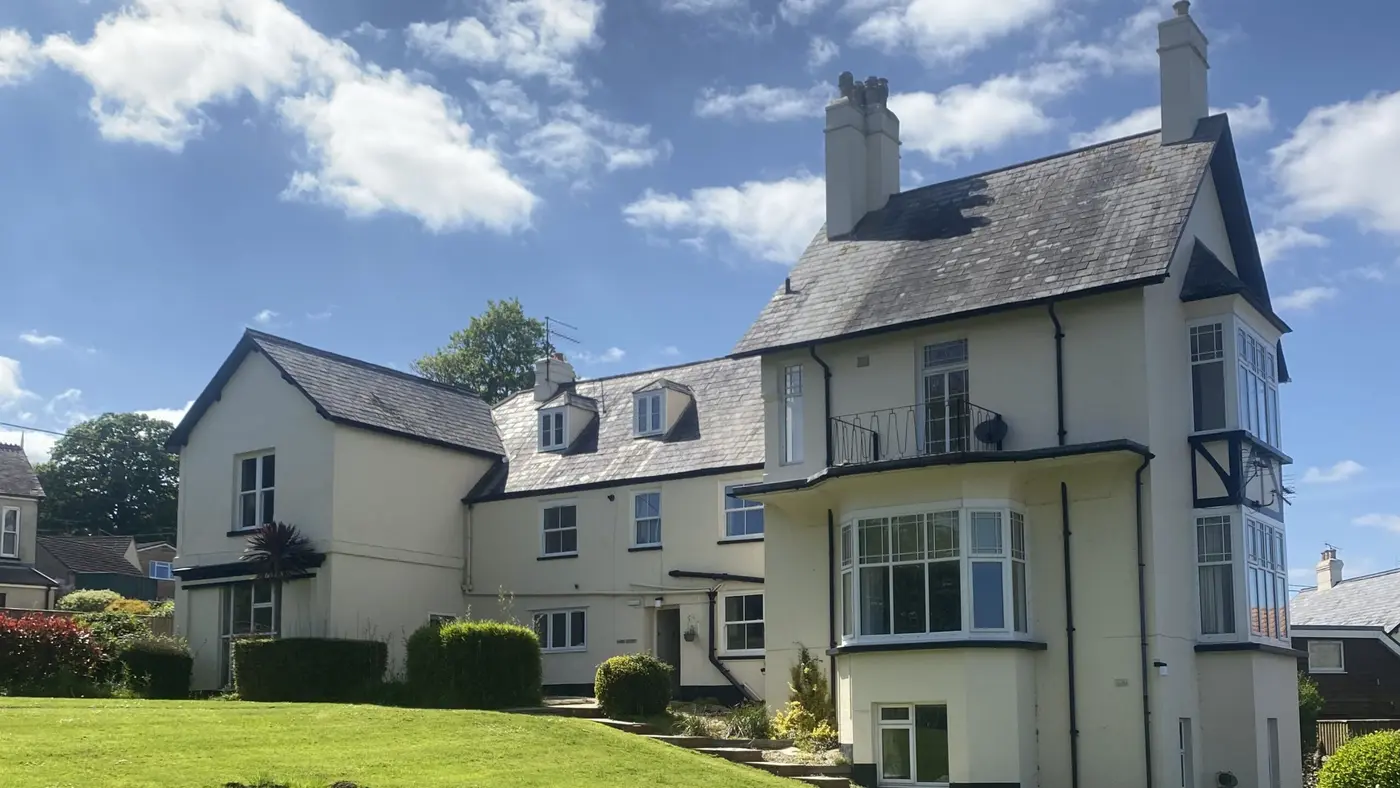
Title split
Commercial to HMO
Informed oversight
You should feel informed and in control. Before you decide, the opportunity should explain how your capital is used, what supports repayment and what happens if the original plan changes.
We can also show you around active refurbishment sites, giving you the opportunity to see the standard of our work and understand how each project is being delivered.
The property, borrower, intended use of funds, proposed legal charge and its ranking are set out for the individual deal.
The primary exit, fallback exit, expected timetable and the route by which capital and interest are repaid are explained.
Review the effect of cost increases, a lower completed value, delays and any extension or default provisions before lending.
Check the valuation basis, comparables, title information, works budget, legal documents and project assumptions.
Agree the reporting timetable, milestone updates and how material delays, cost changes or exit changes will be communicated.
Take the time you need, ask direct questions and obtain your own legal, tax and financial advice before committing capital.
Deal-level due diligence
The brothers behind every deal
Mark structures acquisitions, finance and investor relationships. Martin leads delivery on site. We have made mistakes, solved difficult problems and learned the lessons that only come from remaining active in property—not presenting it from a classroom.
Investor questions
The current focus is on investors considering loans of £400,000 or more.
A typical project is expected to run for approximately 9–18 months. Every opportunity has its own agreed term, exit strategy and extension provisions.
Yes. Property-backed lending places capital at risk. A first legal charge and guarantees may reduce certain risks, but neither guarantees full recovery if the property value, sale or refinance proceeds are insufficient, enforcement is delayed or another documented risk occurs.
The proposed security includes a first legal charge over the property and personal guarantees from the agreed guarantors. The deal documents and solicitors should confirm the borrower, title, charge ranking, any prior debt and the enforcement position before funds are transferred.
The capital, arrangement fee and accrued monthly interest are normally paid together when the loan is redeemed.
Each deal pack explains the intended route to repayment—normally a sale, refinance or other documented property exit—together with the expected timetable and a fallback plan.
The opportunity will show the contingency allowance, downside assumptions, alternative exits and any extension or default provisions. Where Pow Property agrees to fund cost overruns, that commitment will be recorded in the deal documents.
Do not assume that you can. These are normally illiquid, fixed-term loans. Any early-redemption right, extension option or transfer provision will be specific to the legal documents for that opportunity.
Pow Property covers the agreed cost of the loan agreement, first-charge registration and the investor’s independent legal advice.
Investors receive a deal-specific pack containing the borrower and property details, valuation basis, comparables, costs, refurbishment scope, proposed use of funds, return calculation, planned and fallback exits, sensitivity analysis, proposed security and key risks.
The deal documents should set out the reporting timetable, project milestones and escalation process. Material changes to cost, programme or exit should be communicated promptly rather than left until the repayment date.
Do not assume that investor wealth or experience automatically settles the regulatory position or creates protection. The precise position depends on the legal structure, promotion route, parties and documents. The opportunity documentation and independent advisers must state what regulation and protection apply; FSCS or Ombudsman protection should not be assumed.
Illustrative returns are shown gross. Tax treatment depends on your personal or corporate circumstances. Property Pow Brothers does not provide tax advice, so obtain advice from your own qualified adviser.
The deal pack and loan agreement should identify the permitted use of funds, the drawdown arrangements and funds are ring-fenced to the one property reviewed.
We can meet in person or via Zoom and walk you around real, live sites currently undergoing refurbishment. You can see the projects, ask direct questions and understand how we operate before making a decision.
Private investor conversation
No long form and no commitment. We can gather the important information while speaking with you.